When Income Disappears: Why Life Insurance Matters for Homeowners
Buying a home usually reflects a long-term plan: create stability, build equity, and enjoy a future with the people who matter to you.
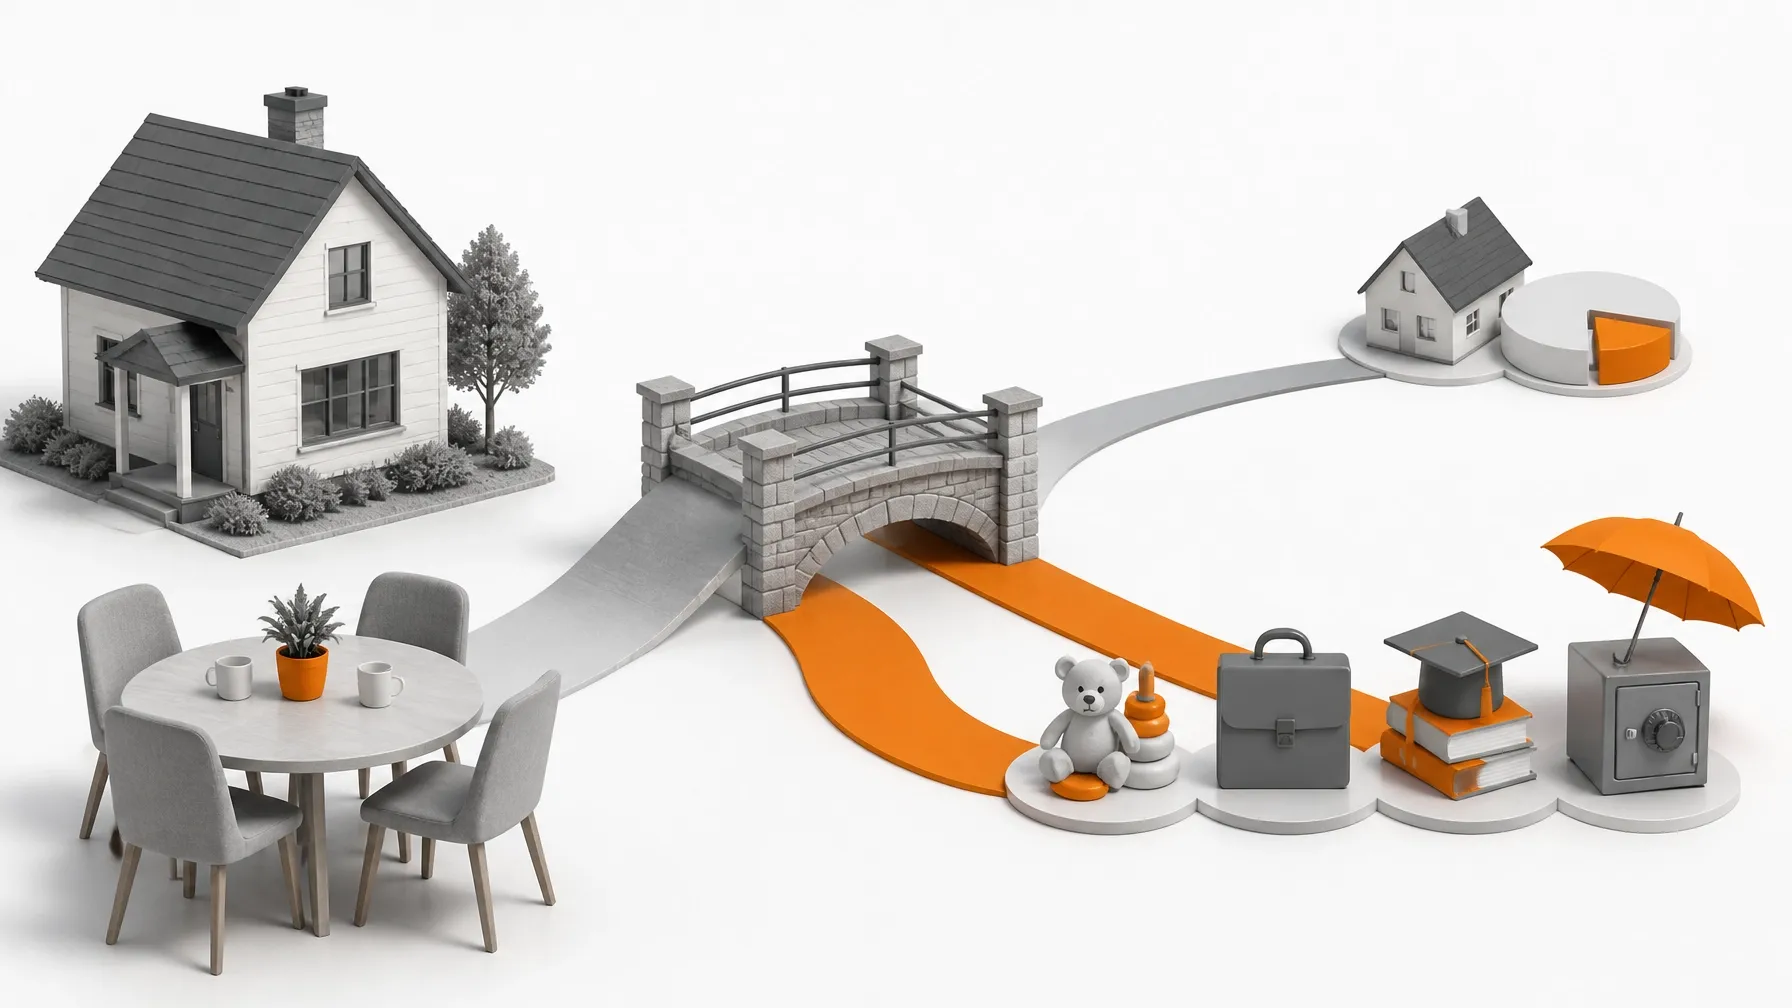
That plan depends on more than the mortgage payment. It may also depend on one person’s income, childcare, caregiving, household work, transportation, meal preparation, or other daily contributions.
If someone dies unexpectedly, those contributions may disappear immediately. The surviving household may still need to manage:
- Mortgage payments
- Property taxes and home expenses
- Utilities and groceries
- Childcare or caregiving
- Other debts
- Education plans
- Final expenses
- Reduced savings and retirement contributions
Life insurance can form part of a household protection plan. The appropriate solution depends on your family, mortgage, income, health, existing coverage, and financial goals.
This article provides general education. It is not insurance advice or a recommendation for any specific product.
Start with the financial risk
A mortgage is one part of the household’s financial obligations. The larger question is:
What would need to be replaced if one person’s income or daily contributions suddenly disappeared?
Consider the following categories.
Mortgage balance
Review the current mortgage balance, including whether the mortgage could increase through refinancing or a future move.
Ask:
- Would the surviving household want to remain in the home?
- Would the mortgage payment remain affordable on one income?
- Would paying down the mortgage reduce financial pressure?
- Would selling the property become necessary?
Insurance does not guarantee that a claim will be approved or that a mortgage will be paid. The policy contract controls eligibility, exclusions, definitions, and claim requirements.
Income replacement
Calculate how much income the household would need to replace and for how long.
The calculation may include:
- Employment income
- Business income
- Bonuses or commissions
- Pension contributions
- Employer benefits
- Government benefits that may change after a death
Income replacement does not need to replicate every future dollar. It should reflect the household’s actual needs, time horizon, available savings, and other resources.
Childcare and caregiving
A person may provide substantial unpaid work. This may include:
- Caring for children
- Supporting an aging parent
- Managing appointments
- Providing transportation
- Preparing meals
- Maintaining the home
- Coordinating school and care arrangements
Replacing these services may require paid support or a reduction in work hours for the surviving partner. Include these costs when reviewing coverage.
Debts and final expenses
Review debts that could remain after death, such as:
- Personal loans
- Credit balances
- Vehicle financing
- Tax obligations
- Funeral and final expenses
The policy proceeds may be used according to the policy structure and beneficiary designation. Confirm the details with a licensed insurance professional.
Education and future goals
Your coverage review may also include:
- Education savings
- Special care needs
- Support for dependants
- Future housing needs
- Emergency reserves
- Retirement funding for the surviving partner
The objective is to identify the financial gap, not to select a coverage amount based only on the mortgage.
Mortgage creditor insurance and personal life insurance
Homeowners may encounter two broad types of protection.
Mortgage creditor insurance
Mortgage creditor insurance is generally connected to a specific mortgage and lender. According to the Financial Consumer Agency of Canada, mortgage life insurance is optional.
Subject to the policy terms, it generally:
- Covers the outstanding mortgage balance or a portion of it
- Pays the lender directly
- Declines as the mortgage balance is reduced
- May have coverage limits
- May include health questions or underwriting requirements
- May end if the mortgage is paid off, transferred, or changed
The lender is generally the beneficiary or recipient of the payment under the creditor insurance structure. The family may benefit from a reduced or eliminated mortgage balance, but it may not receive a cash payment directly.
Review the actual certificate of insurance. Product structures, eligibility, exclusions, benefit limits, and claim requirements vary.
Individually owned life insurance
Personally owned life insurance is a separate policy that is not generally tied to one mortgage or lender.
Subject to the policy terms, it generally:
- Provides a selected coverage amount
- Names one or more beneficiaries
- Can provide funds for the mortgage and other household needs
- May continue if you move or change lenders
- May offer conversion or portability provisions, depending on the policy
- Requires an application and underwriting process
The death benefit is generally paid to the named beneficiary rather than directly to the lender. The beneficiary may then use the proceeds for eligible household priorities, subject to the policy terms and applicable law.
This flexibility can be useful when the household needs more than mortgage repayment. However, personal life insurance also requires decisions about coverage amount, policy term, premiums, underwriting, beneficiaries, and future changes.
Neither option is universally suitable.
Compare the actual coverage
Before choosing coverage, compare the documents rather than relying only on the product name.
| Review item | Mortgage creditor insurance | Individually owned life insurance |
|---|---|---|
| Primary purpose | Protect the mortgage balance | Provide funds to named beneficiaries |
| Beneficiary | Generally the lender | Generally the person or organization named in the policy |
| Benefit amount | May decline with the mortgage balance | May remain level, depending on the policy |
| Use of proceeds | Generally applied to the mortgage | May support mortgage, income, care, education, and other needs |
| Connection to mortgage | Usually linked to a specific mortgage | Generally separate from a specific lender |
| Underwriting | Varies by product and application | Varies by policy and applicant |
| Changes to mortgage | Confirm whether coverage continues | Usually not tied to a mortgage change |
| Cancellation or conversion | Review the certificate and lender terms | Review the policy contract |
| Claim process | Follow insurer and lender requirements | Follow insurer and beneficiary requirements |
The FCAC guidance on optional mortgage insurance products can help you understand the questions to ask.
You can also review educational material such as Canada Life’s mortgage insurance and life insurance comparison. Use these resources for general information, then review the specific policy documents.
Questions to ask before choosing coverage
Use this checklist during a discussion with your lender, insurer, or licensed insurance professional.
Coverage amount
- What amount would the policy pay?
- Does the amount decline over time?
- Would it cover only the mortgage or other household needs?
- Is there a maximum benefit?
- Does the coverage account for future income replacement?
Cost
- What are the premiums?
- Can premiums change?
- Does the benefit change while the premium remains the same?
- What happens if coverage is cancelled?
- Are there additional costs or fees?
Underwriting
- What medical information is required?
- Is a medical examination required?
- When is coverage considered effective?
- Are there exclusions, waiting periods, or contestability provisions?
- What information must be disclosed on the application?
Beneficiaries and control
- Who receives the payment?
- Can beneficiaries be changed?
- Does the lender control the payment?
- Can beneficiaries use the proceeds for childcare, income replacement, or other needs?
- What happens if a beneficiary dies before the insured person?
Mortgage changes
- Does coverage continue if you refinance?
- Does it continue if you change lenders?
- What happens if you sell the home?
- Does coverage end if the mortgage is paid off?
- Would new underwriting be required for replacement coverage?
Future flexibility
- Is the policy portable?
- Is there a conversion option?
- Can coverage be increased later?
- Is the term appropriate for your dependants and mortgage?
- How will the plan be reviewed after a marriage, separation, birth, move, career change, or major purchase?
Review existing protection first
Before adding coverage, gather all current information.
Review:
- Employer-sponsored life insurance
- Individually owned life insurance
- Existing mortgage creditor insurance
- Disability coverage
- Critical illness coverage
- Savings and investments
- Emergency reserves
- Workplace survivor benefits
- Government survivor benefits
Then compare the total available resources with the household’s estimated needs.
Coverage may be inadequate, excessive, unsuitable, or difficult to replace depending on the person’s health and circumstances. An appropriately licensed insurance professional can review suitability, underwriting, policy terms, exclusions, and beneficiary arrangements.
Glenn Bauman Mortgages can help you review the mortgage-related part of your broader financial planning questions and identify when an insurance discussion should be included. Mortgage financing and insurance are separate areas. Obtain insurance recommendations from an appropriately licensed insurance professional.
A practical next step
Complete a household protection review before finalizing or renewing a mortgage.
- Record the current mortgage balance.
- List household income sources.
- Estimate the value of unpaid caregiving and household work.
- List debts and final expenses.
- Identify education and future-care needs.
- Record existing insurance and survivor benefits.
- Compare mortgage creditor insurance with personally owned life insurance.
- Review the actual contracts and policy summaries.
- Confirm suitability with an appropriately licensed insurance professional.
- Revisit the plan when your household or mortgage changes.
The purpose is not to predict every future expense. The purpose is to reduce uncertainty and identify the financial consequences that may follow an unexpected death.
Contact Glenn Bauman Mortgages
For mortgage questions and Canada-wide home financing support:
Mortgage Agent TMG FSRA Lic# M19001990
Best available rates shown are from Glenn Bauman Mortgages lender panel and are subject to your qualification, lender approval, and change without notice. On approved credit (OAC). Your actual rate depends on your credit, down payment, property type, and other lender-specific criteria. Last updated August 29, 2026.
About Glenn Bauman Mortgages
Glenn Bauman Mortgages provides mortgage guidance for Canadians reviewing home financing options and longer-term plans. Contact Glenn to discuss your mortgage requirements.
T: 226-868-9985
E: glenn@glennbauman.com
W: glennbauman.com
Mortgage Agent TMG FSRA Lic# M19001990